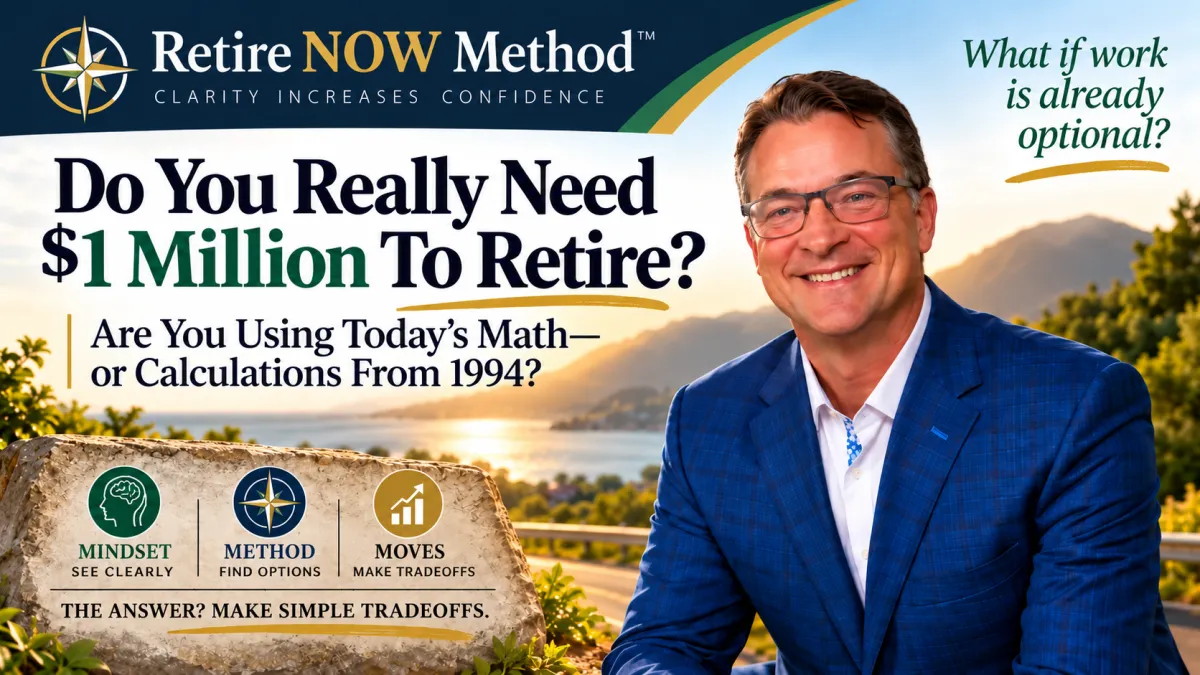
Do You Really Need $1 Million to Retire?
For decades, Americans have been told they need a certain amount of money before they can retire.
Maybe you’ve heard $1 million.
Maybe it’s $1.5 million.
Maybe somebody told you that you need $2 million.
Whatever the number is, something interesting seems to happen:
It’s almost always more than you have right now.
And that can leave people in their late 50s and 60s feeling like they’re behind.
They assume they have to keep working.
But before accepting that conclusion, I think we need to ask a very simple question:
Says Who?
Seriously.
Who decided that your retirement requires $1 million?
Do all retirees have the same income?
The same expenses?
The same Social Security benefits?
The same pensions?
The same mortgage?
The same taxes?
The same lifestyle?
The same dreams?
Of course not.
Imagine two couples who live next door to each other.
Both have exactly $1 million in an IRA.
From that fact alone, can you tell which couple can retire?
No.
One might have a mortgage and the other might own their home outright.
One might have a pension and the other might not.
One household might have two substantial Social Security benefits.
Their monthly expenses could be completely different.
Their desired retirement lifestyles could be completely different.
Knowing someone's account balance doesn't tell you whether they can retire.
That's one of the fundamental ideas behind the Retire NOW Method.
Where Did the $1 Million Idea Come From?
One reason large retirement numbers became so common is the famous 4% rule.
The basic idea is easy to understand.
If you have $1 million invested and withdraw 4% in the first year, that's approximately:
$40,000 of first-year income before taxes.
If you want $80,000 from the portfolio, suddenly the number becomes roughly $2 million.
That's how retirement can quietly become an accumulation problem:
Desired income → divide by a withdrawal percentage → enormous required nest egg.
The 4% rule has been enormously influential, and it can be a useful framework for thinking about withdrawals from an investment portfolio.
But there's another question worth asking:
What if your retirement doesn't have to depend entirely on withdrawals from a variable investment portfolio?
That changes the conversation.
Retirement Is an Income Problem
This is the shift I want people to make.
Instead of beginning with:
How much money do I need?
Begin with:
How much income do I need?
Then determine how much of that income is already available from sources such as Social Security, pensions, rental income, or other reliable income.
What's left is your income gap.
And that is the problem we're actually trying to solve.
A person who needs $7,000 per month and already has $6,000 of reliable monthly income has a very different retirement problem from someone who needs $7,000 and has only $2,000 coming in.
Their investment balances could be identical.
Their retirement situations are not.
This Is Where Mindset, Method and Moves Matter
The Retire NOW Method approaches the problem through three layers:
MINDSET — See Clearly
First, stop assuming that somebody else's retirement number is automatically yours.
See your actual situation.
Your income.
Your expenses.
Your assets.
Your taxes.
Your goals.
Your life.
Clarity increases confidence.
METHOD — Find Options
Once you understand the actual problem, you can start looking for different ways to solve it.
There usually isn't only one path.
The objective isn't necessarily to maximize the amount of money you accumulate.
The objective is to determine what would have to be true for work to become optional.
MOVES — Make Tradeoffs
Then come the choices.
Some people may change how their savings create income.
Others might reduce an expense.
Someone might work part-time instead of full-time.
Another family might change housing.
Someone else might delay one income source while using another sooner.
Sometimes several relatively small moves work together.
That's what I call synergy.
And every move involves some kind of exchange.
You give something to get something.
Liquidity for income.
House size for lower expenses.
A few hours of flexible work for years of freedom from a full-time career.
Sometimes there's even a toll worth paying because what you receive in return is more valuable to you.
People Retire With Less Than $1 Million
I've seen people retire with less than $1 million.
Sometimes far less.
I've seen people in their late 50s and early 60s make retirement work with $250,000, $300,000 or $400,000 in savings.
That does not mean $300,000 is enough for everyone.
That's exactly the point.
There is no universal retirement number.
Those situations worked because the rest of the picture worked.
Their income, expenses, assets, timing and choices fit together in a way that allowed work to become optional.
Someone else with $2 million could have an entirely different situation and need to continue working.
Your Number Isn't the Answer
Maybe you need $1 million.
Maybe you need $2 million.
Maybe you need considerably less.
We can't know until we understand the life that money needs to support.
So if you've been looking at your account balance and thinking:
I don't have enough. I guess I have to keep working.
Don't make that conclusion yet.
Instead, get clear about the income you actually need, the income you already have, and the gap between the two.
Then look at the methods available to you.
Then look at the moves you're willing to make.
Because retirement isn't about reaching somebody else's magic number.
It's about making work optional for you.
And sometimes the difference between working another five or ten years and retiring sooner isn't another enormous pile of money.
It's making a few simple tradeoffs.