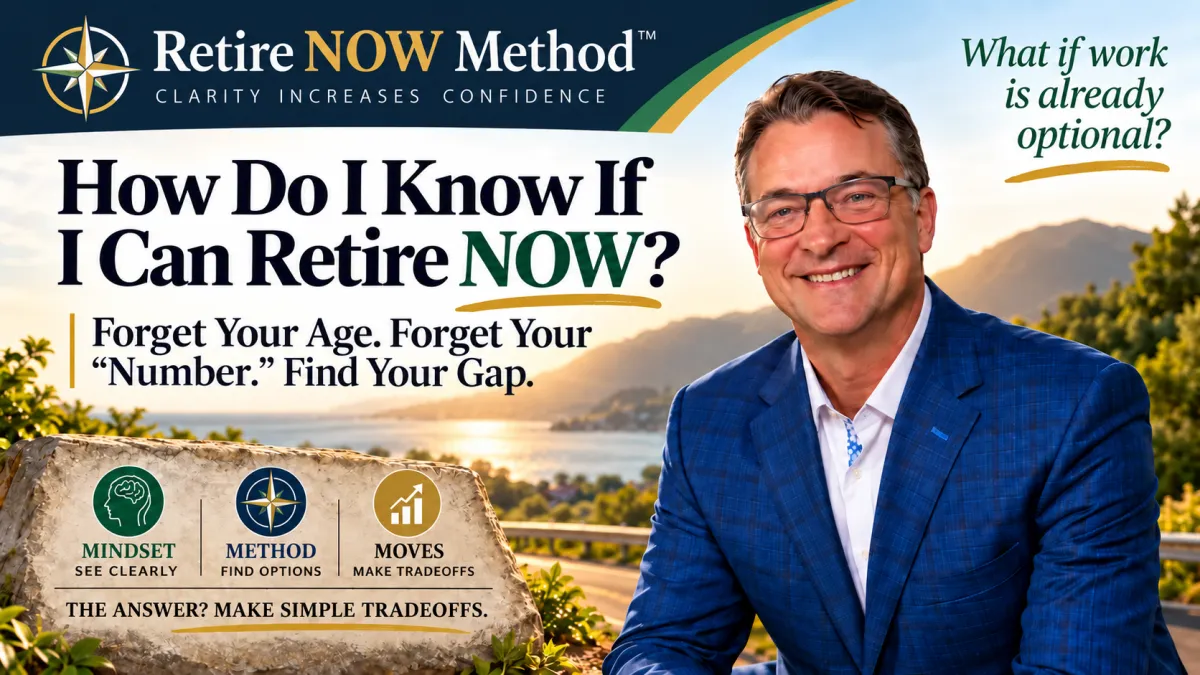
How Do I Know If I Can Retire Now?
Maybe you’re 59.
Maybe you’re 62, 65, or 67.
Maybe you’re waiting for Medicare.
Maybe you’re waiting for full retirement age.
Or maybe you actually like your job. You’re not desperate to leave. You’re simply retirement open.
You’re wondering:
Could I retire now if I wanted to?
That raises a surprisingly important question:
What actually tells you when you’ve arrived?
When you’re driving somewhere with a GPS, eventually it gives you a very clear message:
You have arrived.
Where is that message in retirement planning?
Is it age 62?
65?
67?
70?
Is it when you have $1 million?
$1.5 million?
$2 million?
I think there is a much simpler way to know.
Gap Zero Income
That’s the destination.
And once you understand it, retirement starts looking very different.
Your retirement income gap is simply:
Desired Retirement Income − Reliable Retirement Income = Retirement Income Gap
Suppose you decide you need $7,000 per month to live the retirement you want.
Then you add up your reliable income from Social Security, pensions, rental income, and other sources.
Let’s say that gives you $4,000 per month.
You have a:
$3,000 monthly retirement income gap.
That is a very different problem from asking:
“How do I save another million dollars?”
You don't necessarily need to solve a million-dollar problem.
You need to solve a $3,000-a-month problem.
And there are two basic ways to attack it:
Create more income.
Need less income.
Or, most often, some combination of the two.
That is where the Methods and Moves of the Retire NOW Method begin.
Stop Measuring the Well. Measure the Water.
Imagine you own a farm with a well underneath it.
Which matters more?
How many gallons of water are somewhere underground?
Or whether enough water actually comes out of the well every day to irrigate the farm?
For retirement, your accumulated savings are the well.
Your retirement income is the water flow.
Traditional retirement planning tends to spend an enormous amount of time measuring the well:
How much have you accumulated?
What is your rate of return?
What is your “number”?
Those things matter.
But ultimately, you don't live on an account balance.
You live on income.
A huge reservoir that produces only a trickle of usable water doesn't do much good for the farm.
What matters is whether the water flowing from the well can support the farm you've chosen to live on.
Retirement works the same way.
You Can Work on Both Sides of the Equation
This is where retirement planning gets interesting.
You aren't necessarily stuck with either side of the equation.
There may be ways to increase the amount of reliable income your assets produce.
And there may be conscious tradeoffs you can make that change how much income your retirement requires.
That doesn't automatically mean sacrificing your lifestyle.
A Move could involve housing.
Expenses.
Where you live.
When you claim Social Security.
Whether you work occasionally because you want to.
How your savings are allocated.
How much liquidity you keep.
How you create lifetime income.
There are thousands of possible Moves.
And they don't exist independently.
One Move may make another Move possible.
That's Synergy.
The goal isn't to make your life smaller until you can afford to retire.
The goal is to discover the combination of choices that can create the life you actually want.
Every Dollar Doesn't Need to Do Every Job
There's another problem with the way many people think about retirement savings.
They expect every dollar to do everything.
They want the same dollar to:
stay liquid,
grow,
recover from market losses,
produce retirement income,
pay future taxes,
cover emergencies,
handle healthcare costs,
and eventually become an inheritance.
That's a lot of jobs for one dollar.
Instead, I like to think about giving different dollars different jobs.
I call the three basic jobs:
INCase.
Money available in case life happens.
INCome.
Money whose primary job is producing retirement income.
INCrease.
Money positioned for longer-term growth and future needs.
We'll explore those individually elsewhere in the Retire NOW Library.
For now, the important idea is simple:
Every dollar doesn't have to do every job.
So How Do I Know If I Can Retire Now?
You don't know because you turned 65.
You don't know because you reached some arbitrary account balance.
And you don't know because an online calculator told you your “retirement number.”
You know when you can create enough sustainable retirement income to support the life you've chosen.
That's what I call:
Gap Zero Income.
Your desired income and the income you've created meet.
The gap reaches zero.
You have arrived.
At that point, something important changes.
It doesn't necessarily mean you have to quit your job.
You might love working.
You might want to work part-time.
You might start a business.
You might volunteer.
You might keep doing exactly what you're doing.
But now you're making that decision for a different reason.
Work has become optional.
And that, to me, is retirement.
So instead of asking:
“Do I have enough money to retire?”
Try asking:
“How much income does the life I want require—and how close am I to Gap Zero?”
You may discover that the distance between you and retirement is much shorter than you thought.
What if work is already optional?