How Should Your Money Change When You Retire?
For most of your working life, your retirement money has had a fairly simple job:
Grow.
You put money into a 401(k), IRA, 403(b), or other investment account. You continued contributing. Markets went up and down. When they fell, you had time to wait for a recovery.
Then you retire.
And suddenly, we ask that same pile of money to do something completely different.
Actually, we ask it to do a lot of different things.
We want it to grow.
We want it to replace our paycheck.
We want it available for emergencies.
We want it to recover after market losses.
We want it to keep up with inflation.
We want it available for healthcare.
We want it to last until we're 90, 95, maybe 100.
And we'd really like to leave some of it to our children.
That's a lot of jobs for one pile of money.
Imagine Running a Business This Way
Imagine hiring one employee and saying:
You're responsible for answering the phones, doing the bookkeeping, meeting with clients, making all the sales, cleaning the bathrooms, delivering the products, handling customer service, running the marketing department and growing the company.
Oh—and don't screw any of it up.
That employee would probably have a reasonable response:
You need more employees.
Not because the employee is incompetent.
Because some jobs require different skills, different tools and sometimes even conflict with one another.
Your retirement money isn't much different.
Retirement Changes the Job Description
While you're working, a market decline can actually create opportunity.
You're still earning a paycheck.
You're still contributing.
You aren't necessarily selling investments to buy groceries or pay the mortgage.
So your investments can wait.
But retirement changes the equation.
Now you're withdrawing money.
That means your portfolio may be asked to sell investments during a market decline at exactly the time you would rather leave them alone.
That's what we saw with Bill and Steve.
Both started retirement with $500,000.
Both withdrew $30,000 per year.
Both experienced the exact same 8.25% average return over 20 years.
Yet Steve finished with more than $800,000, while Bill ran out of money in year 16.
The difference wasn't the average return.
It was when the good and bad returns occurred while withdrawals were being taken.
So perhaps the question isn't:
What's the best investment?
Maybe it's:
What job does this money need to do?
Every Dollar Needs a Job
Instead of hiring one employee to run the entire company, what if we hired a team?
That's the idea behind the three jobs I use when thinking about retirement money:
INCome
This is the faucet.
Its job is to create the income that supports the lifestyle you've chosen.
Mortgage.
Groceries.
Electricity.
Gas.
Dinner.
Travel.
Whatever belongs in your chosen retirement lifestyle.
The important distinction is that you're not depending on the rain to pay for groceries.
You're building a faucet.
This money has one primary job: keep the income flowing.
INCase
This is the water tank.
Life doesn't stop surprising us just because we retire.
The roof needs replacing.
The car dies.
A pipe breaks.
There's a medical expense.
Someone in the family needs help.
Your INCase money is there because something eventually happens that wasn't in the monthly budget.
You might simply call this your emergency money.
I call it INCase because its job is exactly what the name says:
It's there in case something happens.
INCrease
This is the reservoir.
Its job isn't to pay this month's electric bill.
Its job is the future.
Inflation.
Healthcare.
Long-term care.
Future opportunities.
Potential inheritance.
And because you aren't constantly draining this money to create your paycheck, you may be able to give it something extraordinarily valuable:
Time.
If markets fall, this money may have the opportunity to wait for a recovery instead of being sold to fund your lifestyle.
So Which One Is Best?
That's like asking whether the plumber, electrician or roofer is the most important person building your house.
You need different people to do different jobs.
Or imagine going to a restaurant and asking:
What's the best food? Protein? Vegetables? Carbohydrates?
That's not how nutrition works.
And it's not how I believe retirement planning works either.
The answer isn't necessarily finding one perfect investment.
It's building a combination of resources designed to accomplish different things.
INCome. INCase. INCrease.
Three employees.
Three jobs.
This Can Change the Retirement Question
And here's where this connects directly to How To Retire NOW.
Suppose you've decided you want $7,000 per month to live the retirement you want.
Right now, your reliable income sources provide $4,000.
That means you appear to have a:
$3,000 monthly income gap.
The traditional response might be:
Keep working. Keep saving. You need more money.
But before reaching that conclusion, I want to know something else.
What happens if we give some of the money you've already accumulated the specific job of creating income?
How much income can it create?
Maybe it closes $500 of the gap.
Maybe $1,500.
Maybe all $3,000.
We don't know until we actually do the math.
That's why I don't believe retirement begins with some arbitrary account balance or magic age.
It begins with clarity.
Give every dollar a job.
Recalculate the income.
Then look at the gap again.
Your Money Changed Jobs. Your Plan May Need to Change Too.
The day you retire, your financial life fundamentally changes.
For decades, you were primarily putting money in.
Now you need your accumulated resources to help send money back out.
That doesn't mean growth stops mattering.
It means growth is no longer the only job.
And asking one pile of money to simultaneously provide income, liquidity, growth, inflation protection, emergency reserves and inheritance may create risks you don't actually need to take.
Instead:
INCome keeps the faucet running.
INCase handles life's surprises.
INCrease gets time to work on the future.
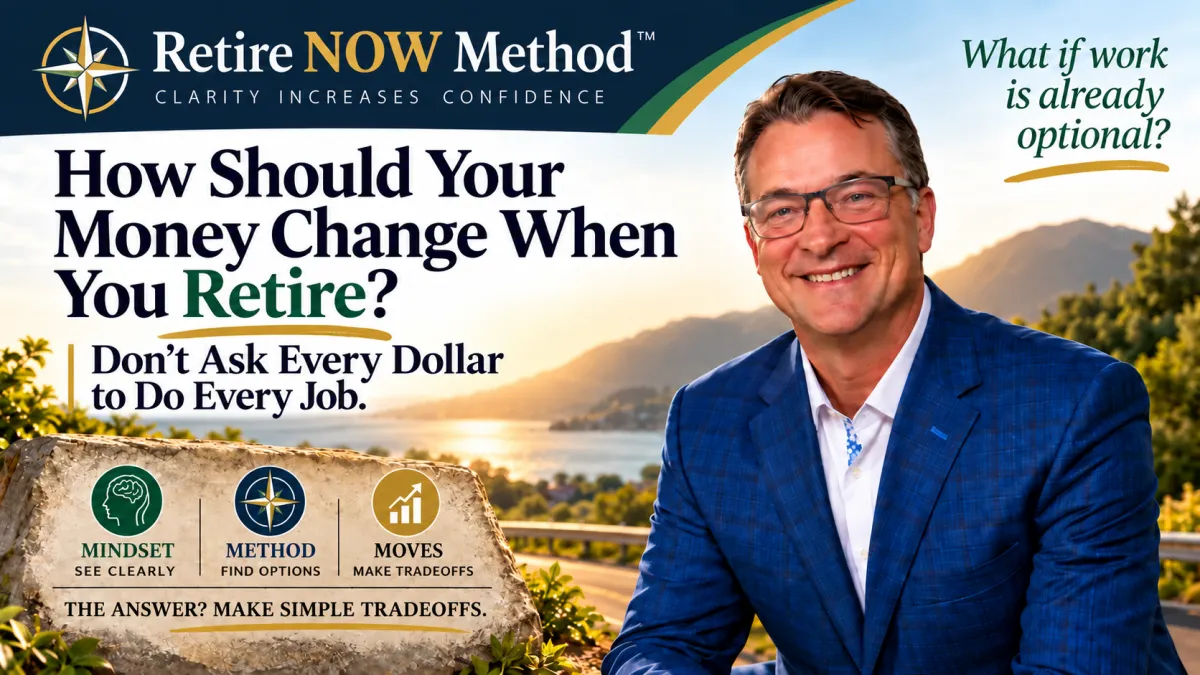
That is one of the biggest shifts in the Retire NOW Method:
Don't ask every dollar to do every job.
Give each dollar a job it is actually equipped to do.
Then ask the question that matters:
What if work is already optional?