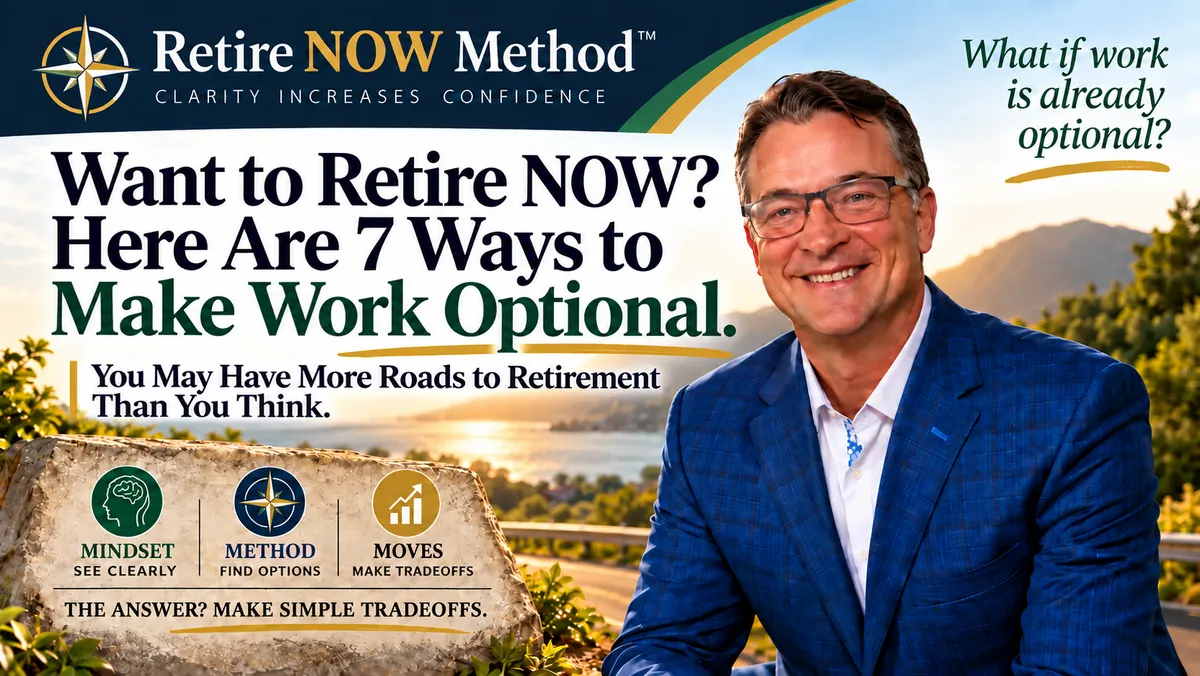
Want to Retire Now? Here Are 7 Ways to Make Work Optional
Want to Retire Now? Here Are 7 Ways to Make Work Optional
Once you start thinking about retirement as an income problem instead of an accumulation problem, an interesting question appears:
What if there’s more than one way to close your Retirement Income Gap?
Imagine you want $7,000 a month to live the life you want in retirement.
Between Social Security, a pension, rental income or other dependable sources, you already have $4,000 a month coming in.
That leaves a $3,000 Retirement Income Gap.
A traditional approach might immediately turn to your investment accounts and ask:
How much money do I need to accumulate to produce another $3,000 a month?
And if the answer seems too large, the conclusion may be:
Keep working. Keep saving. Wait.
But those aren't necessarily the only choices.
The METHODS portion of the Retire NOW Method is about finding the other roads that may be available.
I call them Maybe Moves.
They're not recommendations.
They're not commitments.
They're simply possibilities worth understanding before you decide which road you want to take.
I organize those possibilities into seven categories.
1. Money Moves
A Money Move happens when money actually moves from one place to another to help close your Retirement Income Gap.
Sometimes that means using a portion of retirement savings to create dependable lifetime income.
Instead of thinking only about your 401(k), IRA or investment account as a pile of money, you can ask:
Could some of this money do a better job for me as income?
Another example might be paying off a mortgage.
Imagine someone has $60,000 remaining on a mortgage and is making roughly $16,000 a year in payments.
One possibility is to leave the $60,000 invested and continue making the mortgage payment.
Another possibility is to use $60,000 to eliminate the mortgage and therefore eliminate roughly $16,000 a year of expenses.
I'm not saying everyone needs to pay off their mortgage. I don't even personally believe that paying off a mortgage is automatically the best choice.
The point is that it's a road.
Money can potentially be repositioned to create income or eliminate an expense.
That's a Money Move.
2. Expense Moves
Some expenses you have while working may not follow you into retirement.
Maybe you're contributing hundreds or thousands of dollars each month to retirement accounts.
Maybe you commute to work.
Maybe you maintain a second vehicle because two people in the household need to get to work every day.
Maybe there are work clothes, dry cleaning, lunches, subscriptions or other expenses that aren't as important once your life changes.
And then there are expenses that simply deserve another look.
You might own a vacation home that costs a substantial amount every month.
Selling it could reduce your expenses considerably.
But maybe retirement means you'll finally have enough time to enjoy that vacation home.
Then keeping it may become more important to you, not less.
That's why an Expense Move isn't about cutting everything you enjoy.
It's about asking:
Which expenses belong in the life I want next?
3. Time Moves
Sometimes you don't need to change what you own.
You need to change when you use it.
Social Security is an obvious example.
You might claim earlier and receive a smaller monthly benefit sooner.
Or you might use other resources for several years and delay Social Security to receive a larger benefit later.
Neither answer is automatically right.
They're different roads with different tradeoffs.
Time Moves can also involve how you use your savings.
Instead of treating every retirement dollar exactly the same, you might designate money for different periods of retirement.
Perhaps one portion is designed to provide income during the first several years.
Another portion is positioned for the following years.
And money you don't expect to need for a decade or more may have more time to remain invested.
Timing can also involve employment milestones, pension dates, birthdays, annuity anniversaries or other events that could materially change your retirement options.
Sometimes the difference between two retirement dates isn't five years.
It might be a few months.
4. Housing Moves
Housing is often one of the largest expenses in retirement.
That makes it one of the largest variables we can examine.
Maybe the kids have moved out and you're living in a five-bedroom, two-story house that no longer fits the life you want.
Downsizing could reduce your mortgage, property taxes, insurance, maintenance and utility costs.
Or maybe you love your home and don't want to leave it.
Could part of it produce income?
I personally live in a duplex and rent bedrooms month-to-month.
That's one example.
Other people might choose an accessory dwelling unit, roommate arrangement, RV lifestyle or another housing configuration.
A Housing Move doesn't necessarily mean moving across the country.
It simply means asking:
Does my current housing arrangement help or hurt my ability to make work optional?
5. Occupational Moves
Retiring from your full-time career doesn't necessarily mean you can never earn another dollar.
That's an artificial choice we sometimes impose on ourselves:
Work full-time or never work again.
There are a lot of possibilities between those two extremes.
Maybe you consult.
Maybe you work seasonally.
Maybe you turn an existing skill into freelance income.
Maybe you work somewhere part-time because you actually enjoy it.
Maybe you use gig work such as Uber, Lyft, DoorDash, Instacart, Amazon Flex or another flexible platform when you feel like working.
In the Retire NOW Method, I tell the story of a grandfather who could earn some extra income delivering groceries while spending time with his granddaughter.
His daughter gets time to work on her master's degree.
He gets time with his granddaughter.
And the household creates some additional income.
That's more than a financial equation.
That's a life equation.
An Occupational Move asks:
Could a little income I enjoy earning replace years of income I don't enjoy earning?
6. Distance Moves
Sometimes the biggest retirement variable isn't your portfolio.
It's your ZIP code.
You might move twenty or thirty minutes away from an expensive metropolitan area and dramatically change your housing costs without dramatically changing your life.
You might move to another state.
Or another country.
I've lived in San Diego, Mexico and Colombia, so I've personally experienced how dramatically geography can change the cost of everyday life.
There are places where housing, transportation, food and entertainment can cost considerably less than they do in many parts of the United States.
That doesn't mean everyone needs to move to another country.
For some people, leaving their family and community would be a toll they're completely unwilling to pay.
That's fine.
Remember:
These are Maybe Moves.
We're discovering roads, not choosing them yet.
7. Synergy
This is where I think the Retire NOW Method becomes especially interesting.
Most people aren't going to close a $2,000 or $3,000 monthly Retirement Income Gap with one miraculous decision.
They may not need to.
Maybe a Money Move creates $700 a month.
An Expense Move eliminates $400.
A Time Move creates another $600.
A little part-time work produces $500.
And a Housing Move saves another $300.
Individually, none of those decisions retires you.
Together, they might.
That's Synergy.
Instead of searching for one giant solution, we begin combining ordinary decisions.
A little more income here.
A little less expense there.
A change in timing.
A housing decision.
Some enjoyable part-time work.
Maybe a change in geography.
There are thousands of possible combinations.
And your combination doesn't have to look anything like somebody else's.
METHODS Are About Possibility
This is an important distinction.
At this stage, we aren't deciding what you will do.
We're discovering what you could do.
That's why I call these Maybe Moves.
Maybe you'd consider downsizing.
Maybe you'd never consider it.
Maybe part-time work sounds fantastic.
Maybe the whole reason you're retiring is because you never want to work another day.
Maybe you'd happily move to another state.
Maybe living five minutes from your grandchildren is non-negotiable.
Those answers are yours.
My job isn't to choose your road.
It's to help you see the roads that are actually available.
That's why the METHODS portion of the Retire NOW Method is your Financial GPS.
Your MINDSET helps clear your Financial Windshield so you can see where you are.
Your METHODS reveal the roads that could potentially take you where you want to go.
And then comes MOVES:
Which road do you actually want to take?
Sometimes people discover that working longer really is the road they prefer.
But sometimes they discover something very different:
A faster route may already be available.
Want to learn more?
Visit RetireNowMethod.com
Have a retirement question you'd like me to answer?
What if work is already optional?
Charlie Jewett
Creator, The Retire NOW Method