Want to Retire Now? Change How You Think About Retirement
Want to Retire Now? You May Need to Change How You Think About Retirement
Most people I’ve met with during my career come into retirement planning with essentially the same question:
How much money do I need to save before I can retire?
A million dollars?
$1.5 million?
$2 million?
After more than two decades in retirement planning, I’ve learned to start somewhere else.
If you want to retire now—or simply sooner than you thought—you may first need to change the way you think about retirement.
The MINDSET portion of the Retire NOW Method is built around three ideas.
1. Retirement Is an Income Problem, Not an Accumulation Problem
This is probably the biggest change in thinking.
Retirement isn't really about accumulating some predetermined amount of money.
It's about replacing your paycheck.
Imagine going to work on Friday and receiving the income that supports your life.
Then imagine retiring.
When Monday morning arrives, your bills haven't retired. You still need groceries. You still need electricity. You still want to travel, eat out, help your family and enjoy your life.
What you need is income.
That's why I prefer a different question:
What would it take to make my paycheck optional?
Start with the amount of monthly income you want in retirement.
Then identify the dependable income you already have available from sources such as Social Security, pensions, rental income or other dependable income.
The difference is what I call your Retirement Income Gap.
That's the problem we're actually trying to solve.
Instead of saying, "I only have $700,000, so I guess I can't retire," we can ask:
How much income does that $700,000 actually need to produce?
That's a very different conversation.
2. Time Is More Valuable Now
Money matters.
But money isn't the only thing you're spending when you decide to work another five years.
You're spending time.
The next five years are the youngest five years of the rest of your life.
Your health may be better.
Your spouse's health may be better.
Your parents may still be alive.
Your grandchildren may still be young enough to think spending Saturday with Grandma and Grandpa is the greatest thing in the world.
There are no guarantees about what life looks like five, eight or ten years from now.
That doesn't mean everyone needs to retire immediately.
Sometimes continuing to work is absolutely the tradeoff someone wants to make.
But I think the cost of waiting deserves to be included in the calculation.
We spend enormous amounts of time asking:
Can I afford to retire?
There's another question worth asking:
Can I afford to keep waiting?
3. Retirement Planning Has Evolved
Think about how much the world has changed since the 1990s.
Think about your first cell phone compared with the phone in your pocket today.
Think about computers.
Movies.
The internet.
Artificial intelligence.
Almost everything around us has evolved.
Retirement planning has evolved too.
Yet many people are still making retirement decisions using ideas that became popular decades ago.
One of the best examples is the 4% rule.
The research behind the original 4% rule was published by William Bengen in 1994. It became an incredibly useful benchmark for thinking about sustainable withdrawals from an investment portfolio.
And it's still useful.
But 1994 doesn't have to be the end of the conversation.
The income strategies and financial products available to retirees have continued to evolve.
That gives us more possibilities to explore.
Instead of automatically assuming you need to accumulate more money and work more years, we can look at the resources you already have and ask whether there may be another route.
The Retire NOW MINDSET
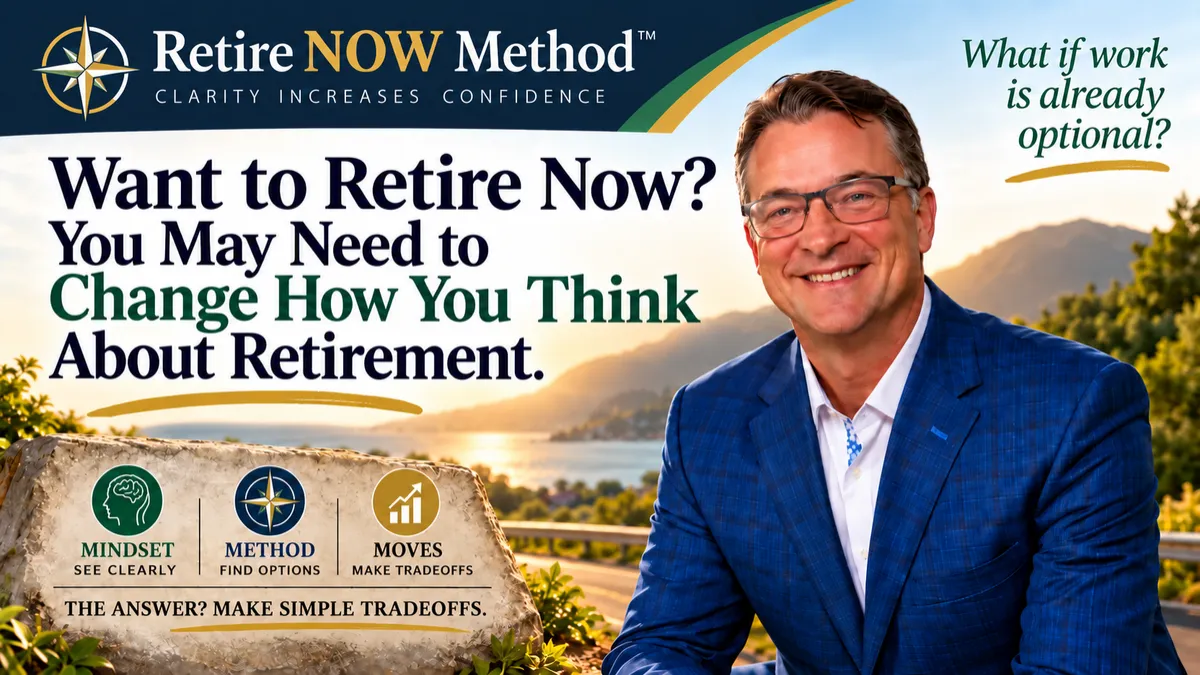
So the MINDSET portion of the Retire NOW Method comes down to three changes in thinking:
Retirement is an income problem, not an accumulation problem.
Time is more valuable now than it will ever be again.
Our retirement thinking can evolve as the tools and strategies available to us evolve.
None of that means you can retire today.
Maybe you can.
Maybe you can't.
The first step isn't deciding.
The first step is seeing clearly.
That's why I call the first part of the Retire NOW Method your Financial Windshield.
Before we start choosing roads, we need to see where you actually are.
And sometimes, once the windshield clears, people discover something they weren't expecting:
Work may already be optional.
Want to learn more?
Visit RetireNowMethod.com
Have a retirement question you'd like me to answer?
What if work is already optional?
Charlie Jewett
Creator, The Retire NOW Method