What If We Run Out of Money?
It may be the most common fear in retirement.
What if we run out of money?
And here's something I've learned after years of talking with people about retirement:
That fear doesn't necessarily disappear when you accumulate more money.
I've seen people with relatively modest savings worry about running out.
I've seen people with millions of dollars worry about running out.
I've even seen extraordinarily wealthy people worry about running out.
Why?
Because the fear isn't really about a number.
It's about the paycheck.
For Most of Your Life, Money Has Been Replaceable
Think about the way money has worked throughout your adult life.
You earn a paycheck.
You spend some of it.
Then another paycheck arrives.
You pay the mortgage. You buy groceries. You take a vacation. You replace the car.
And then you go back to work and earn more money.
In a strange way, your job has been like a money tree.
As long as you keep showing up and doing your job, more money grows.
Then retirement arrives.
You leave work on Friday.
Monday morning comes.
And there is no paycheck.
That's when the psychology changes.
Suddenly, money doesn't feel replaceable anymore.
Now every dollar you spend can feel like a dollar you'll never get back.
And that's where a lot of retirement fear begins.
The Swimming Pool Problem
Imagine that you spent 30 or 40 years filling a giant swimming pool.
That pool represents your retirement savings.
Then you retire.
Now instead of filling the pool, you're pumping water out of it every month to live.
Mortgage.
Food.
Travel.
Healthcare.
Everything.
And every month you watch the water level.
Maybe some rain falls into the pool.
That's investment growth.
Interest.
Market returns.
But there's a problem:
You don't control when it rains.
If enough rain falls, everything may work beautifully.
But what happens when you're pumping water out faster than nature puts it back?
The water level falls.
And that's frightening.
That's why I don't think the question is simply:
“How much money do I have?”
There's another question:
“How am I going to replace the paycheck?”
You're Probably Not Afraid of Running Out of Money
This distinction matters.
Imagine that you're 92 years old and your investment account reaches zero.
Sounds terrifying.
But now imagine that the account reaches zero—and the next month your retirement income still arrives.
And the month after that.
And the month after that.
For as long as you live.
Those are two completely different problems.
That's why I say:
Most people aren't actually afraid of running out of money. They're afraid of running out of income.
The account balance matters.
But the account balance and the income it produces are not the same thing.
And confusing those two things can cause people to work years longer than necessary or spend retirement terrified to use the money they spent their entire lives accumulating.
What If You Built a Well Instead?
Instead of imagining retirement as a swimming pool, imagine a well.
A pool contains a finite amount of water.
You pump from it.
The level falls.
You hope enough rain comes along to refill it.
A well works differently.
You pump water from the well, but the water source continues replenishing it.
That's a much better metaphor for the way I want people to think about retirement income.
Don't just build a bigger pool. Build a better well.
The objective isn't necessarily to die with the biggest possible reservoir of unused money.
The objective is to create enough reliable income to support the life you actually want to live.
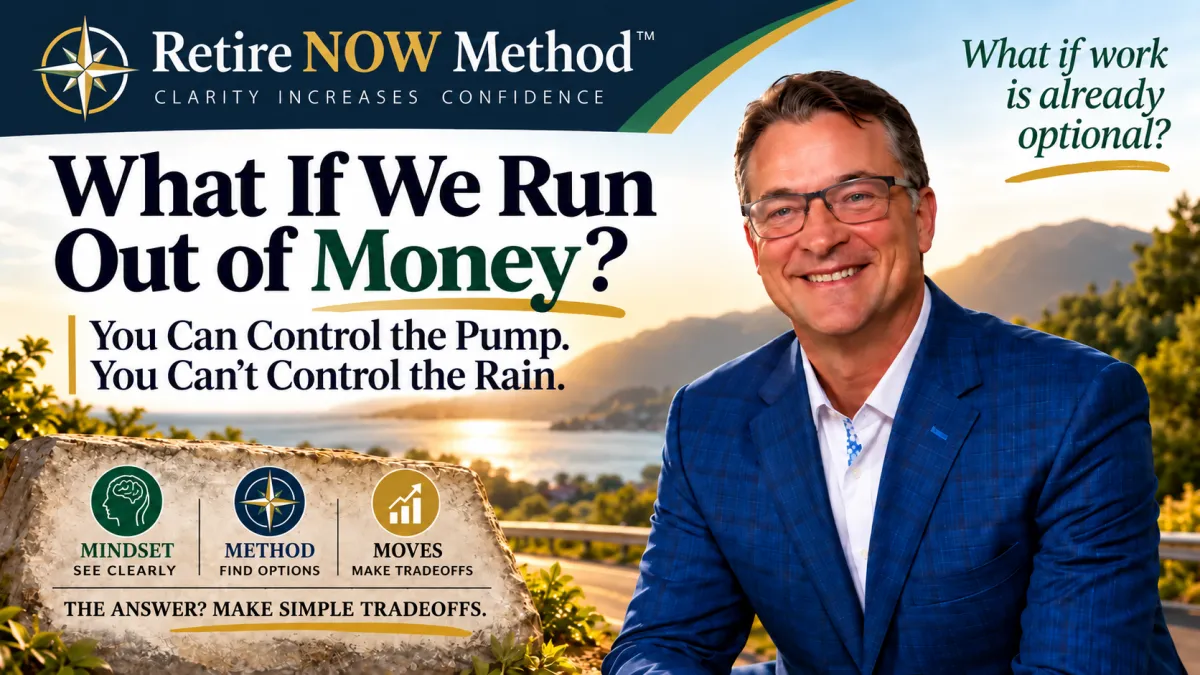
You Can Control the Pump. You Can't Control the Rain.
This may be the most important sentence in this entire discussion:
You can control the pump, but you cannot control the rain.
You don't control what the stock market will do next year.
You don't control interest rates.
You don't control the exact returns your investments will earn over the next 30 years.
You don't know exactly how long you'll live.
And none of us knows precisely how much money will ultimately remain for our heirs.
But that doesn't mean everything about retirement has to be left to chance.
There are choices and tradeoffs available that can change how your retirement income is created.
That's where the Retire NOW Method comes in.
Mindset. Method. Moves.
First comes Mindset:
See clearly.
Instead of asking only how big your account balance is, recognize the problem you're actually trying to solve.
You need income.
Then comes Method:
Find options.
There isn't only one way to turn a lifetime of savings into retirement income.
And then come the Moves:
Make tradeoffs.
Every retirement strategy involves exchanges.
Liquidity.
Growth potential.
Guarantees.
Legacy.
Income.
Flexibility.
Risk.
There isn't one universally correct combination.
The question is which tradeoffs make sense for your life.
That's why clarity comes before advice.
The Goal Isn't Necessarily to Protect Every Dollar
There's an uncomfortable contradiction in traditional retirement thinking.
People spend decades accumulating money specifically for retirement.
Then retirement arrives—and they're terrified to spend it.
So they reduce their lifestyle.
They skip trips.
They worry about purchases.
Sometimes they even go back to work.
All because watching the account balance fall feels dangerous.
But what if some of that money could do the job you originally accumulated it to do?
Create income.
That doesn't mean every dollar needs to become income.
It doesn't mean giving up liquidity.
It doesn't mean abandoning growth.
It means recognizing that different dollars can have different jobs.
Some money may need to remain available.
Some may need to grow.
And some may need to create income you cannot outlive.
The solution can be a combination.
So, What If You Run Out of Money?
That's the wrong question—or at least an incomplete one.
The more useful question is:
What happens to my income if I live much longer than expected or spend down my assets?
That's something we can actually design around.
You may not be able to guarantee how much money will ultimately remain in your accounts.
But you can make conscious choices about how much of your retirement lifestyle depends upon constantly withdrawing from a finite pool.
That's the tradeoff.
And for some people, exchanging some access to capital or some potential upside for more dependable lifetime income can dramatically change the retirement equation.
Because retirement isn't simply about accumulating the biggest pile of money possible.
Retirement is an income problem.
And when you solve the income problem, something interesting can happen:
The fear of watching the pool slowly drain can begin to disappear.
Maybe you don't need a bigger pool.
Maybe you need a well.
And maybe work has already become optional.