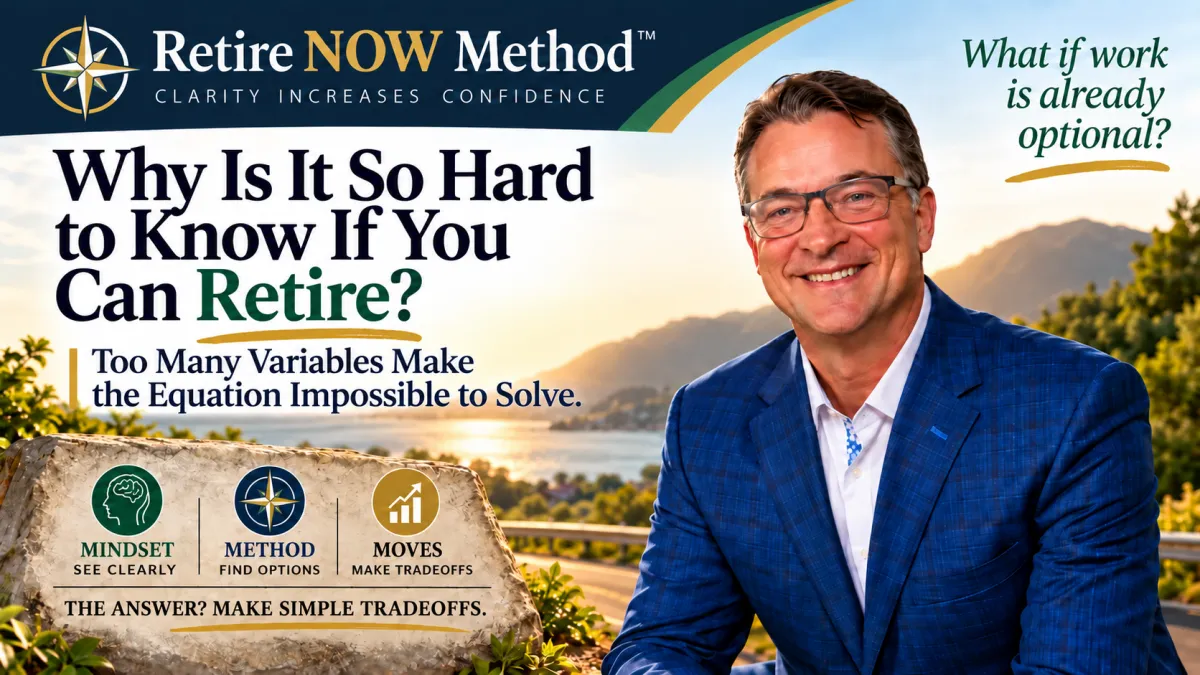
Why Is It So Hard to Know If You Can Retire?
Retirement planning can feel ridiculously complicated.
How long will you live?
How long will your spouse live?
What will the stock market earn?
When will the next crash happen?
How long will it take to recover?
What will inflation be?
What will tax rates be?
What will healthcare cost?
Will you need long-term care?
What will Medicare cost?
What will Social Security look like?
How much will you actually spend?
What happens when one spouse dies?
Will your children or grandchildren need financial help?
How many cars will you replace?
What happens if you live ten years longer than you expected?
And that's not even the whole list.
No wonder people approaching retirement keep asking:
How am I supposed to know if I can retire when I don't know any of this?
There's a reason it feels impossible.
It's algebra.
X + 5 = 10
I come from a math family.
My dad is a physics professor and author of college textbooks. My brother was a professor at Harvard. And my mom taught algebra for more than 30 years.
She actually retired—and then went back to teaching for another 13 years.
Her story is one of the reasons I care so much about helping people figure out whether work might already be optional.
So forgive me while we do a little algebra.
Suppose I give you this equation:
X + 5 = 10
What's X?
Easy.
5.
We know one side of the equation. We know the 5. We know the total is 10.
So we can solve for X.
Now I'm going to make one tiny change:
X + Y = 10
What's X?
We don't know.
Maybe X is 5.
Maybe it's 3.
Maybe it's 8.
We turned one known number into another variable, and suddenly an incredibly simple equation became much harder to solve.
That's retirement planning.
Retirement Has Too Many Variables
Traditional retirement planning asks us to make decisions today based on an enormous number of things we can't possibly know.
We don't know exactly how long we'll live.
We don't know future market returns.
We don't know the sequence in which those returns will occur.
We don't know future inflation, tax rates, healthcare expenses or emergencies.
And yet somehow we're supposed to put all of those variables into a financial plan and get a precise answer to:
When can I retire?
That's why the answer can feel so elusive.
We're trying to solve for X when half the equation is made up of Ys.
But here's the good news:
You don't have to know everything.
Some Variables Are Outside Your Control
There are variables you simply don't control.
You don't control the stock market.
You don't control inflation.
You don't control future tax law.
You don't know exactly how long you'll live.
Trying to turn those things into certainties doesn't make much sense.
That's also why I believe a retirement plan has to be dynamic.
You revisit it.
You adjust it.
When life changes, the plan changes.
But there is another category of variables that matters much more for answering the question we're asking.
There Are Variables You Can Control
Most of the variables you can actually do something about ultimately affect one of two things:
Income and expenses.
And those two numbers are incredibly powerful.
You can make decisions about when to begin Social Security.
You can choose whether to use savings temporarily and delay Social Security.
You can decide how different portions of your retirement savings will be used.
You can decide whether some money is intended for growth, some for liquidity and some for income.
You can change expenses.
You can change housing.
You can work differently.
You can move.
You can make dozens of small decisions that change either the income side or the expense side of your retirement equation.
Those are Moves.
And every time you turn an unknown into something more predictable, the equation becomes easier to solve.
Turn the Ys Into 5s
Remember:
X + Y = 10
is difficult to solve.
But:
X + 5 = 10
is easy.
That's what we're trying to do with retirement.
We don't need to eliminate every unknown in your life.
We need to identify the variables we can influence and begin turning some of them into knowns.
Suppose you determine exactly what your Social Security income will be at a particular claiming age.
That's one less variable.
Suppose you create a known amount of retirement income from part of your portfolio.
Another variable becomes more predictable.
Suppose you eliminate a major monthly expense.
The equation changes again.
One move might not completely close your retirement income gap.
That's okay.
Make another.
And another.
Sometimes several relatively small changes create a very large result.
Retirement Is an Income-and-Expense Equation
This is why I don't believe the most useful first question is:
How much money do I need to retire?
There are too many variables hiding inside that question.
I would rather start with:
How much income do you want?
Then:
How much reliable income will you already have?
The difference is your income gap.
Now we have something we can actually work on.
Instead of trying to predict 30 years of markets, inflation, tax rates, longevity and healthcare expenses perfectly, we can begin looking for Moves that change the equation.
Increase income.
Reduce expenses.
Change timing.
Change where or how you live.
Change how some of your money works.
Keep making choices until the gap reaches zero.
That's when the retirement question starts becoming much easier to answer.
You Don't Need to Solve Every Variable
This may be the most important part.
Clarity doesn't require certainty about everything.
You don't have to know what the stock market will do in 2037.
You don't have to know exactly how long you'll live.
You don't have to correctly predict every tax law Congress will pass during your retirement.
You need to understand what you can control, make thoughtful choices about those variables, and build a plan capable of changing when life changes.
That's much more achievable.
And sometimes, after turning just a few unknowns into knowns, something surprising happens.
The equation that looked impossible suddenly becomes pretty simple.
And the answer may be:
You can retire now.