Will You Pay More or Less Taxes in Retirement?
There are two questions I’ve asked people for more than 20 years.
They’re simple questions.
But when you put the answers together, they can completely change the way you look at retirement taxes.
Here’s the first:
Do you believe taxes will be higher or lower during your retirement than they are today?
I’m not asking you to predict Congress.
I’m not asking you to become a tax expert.
I’m asking what you believe.
Think about the 20, 30, or even 40 years you could spend in retirement.
Do you believe tax rates will generally be higher than they are today?
Or lower?
Hold onto your answer.
Because now I want to ask you something else.
Will You Need More Income—or Less?
Imagine you're 20 years into retirement.
Do you think the same amount of money you needed when you retired will still buy the same groceries, gasoline, travel, healthcare, entertainment, and lifestyle?
Or do you believe you'll need more income?
Again, there isn't a correct answer I'm trying to get you to give me.
I want your answer.
But here's where this gets interesting.
If your answers are:
I think taxes may be higher.
and
I think I'll need more income.
then I have a third question for you:
Why Are You Postponing Taxes Until Later?
For decades, Americans have been encouraged to put money into traditional IRAs, 401(k)s, 403(b)s, and other tax-deferred retirement accounts.
The basic agreement is pretty simple:
You don't pay the income tax now. You pay it later when you take the money out.
That can be an extremely useful agreement.
Employer matching can make it especially attractive. If your employer is putting additional money into the account because you contribute, that deserves to be considered separately.
But I want you to see the underlying exchange clearly.
You haven't necessarily eliminated the tax.
You've postponed it.
And if you simultaneously believe taxes could be higher later and that you'll need to withdraw more income later, it's worth asking:
Is postponing those taxes consistent with what I actually believe?
That's a very different question from:
What did somebody tell me to do 25 years ago?
“You'll Be in a Lower Tax Bracket When You Retire.”
Says who?
That's one of those retirement-planning assumptions that gets repeated so often it begins to sound like a law of nature.
But it isn't.
You may be in a lower tax bracket.
You may not.
Your situation could change substantially when you retire. You may no longer be making deductible retirement-plan contributions. Your mortgage situation may change. Your children may no longer be dependents. At the same time, you may begin taking taxable distributions from accounts you've spent decades accumulating.
That's why I don't want to begin with the assumption that you'll pay less tax in retirement.
I want to begin with your situation.
Think of Your IRA as an Agreement
I like the word agreement because it changes the way we think about tax-deferred money.
Suppose you have $500,000 in a traditional IRA.
How much of that $500,000 is actually yours to spend?
We don't completely know yet.
The account has a future tax liability attached to it.
When you withdraw money, the tax rules in effect at that time help determine how much you keep.
So in a sense, you've entered into an agreement:
“I'll postpone paying the tax today, and we'll determine the tax when I take the money out later.”
Maybe you love that agreement.
Great.
But maybe, after answering those first two questions, you realize:
Wait a minute. I don't know if I want that agreement anymore.
And that's where retirement planning gets interesting.
Agreements Can Change
You can't go backward and change the decisions you made 10, 20, or 30 years ago.
But you can make different decisions going forward.
Depending on your circumstances, there may be strategies for deliberately paying taxes on some tax-deferred money now and moving it into an account structure where qualified future distributions can be tax-free.
That might happen all at once.
It might happen gradually over five years.
It might happen over ten years.
The appropriate strategy depends on your income, tax bracket, account types, age, Medicare considerations, current tax law, and a lot of other variables.
The point isn't:
“Everybody needs to convert everything.”
The point is:
You have a choice.
You can examine the agreement instead of simply assuming the agreement you inherited decades ago still makes sense today.
Net Income Is What Actually Pays Your Bills
This matters enormously to the Retire NOW Method because retirement is an income problem.
Suppose you've created $3,000 per month of retirement income.
That's useful information.
But if that $3,000 is taxable, what actually reaches you?
$2,700?
$2,500?
$2,300?
The number that pays the mortgage, buys groceries, pays the electric bill, and funds your life isn't your gross income.
It's your net income.
And future taxes introduce another variable into that calculation.
That's why creating tax-free income can be such a powerful Move for the right person: it can remove one of the variables from the retirement-income equation.
If $3,000 comes out tax-free, your spendable income is $3,000. That's a number we can actually use when we're trying to determine whether your income gap has reached zero.
So, Will You Pay More or Less Taxes in Retirement?
I don't know.
And neither does anyone else with certainty.
But that's not the question I need you to answer today.
I want you to answer these:
Do I believe taxes will generally be higher or lower during my retirement?
Do I believe I'll need more or less income as retirement progresses?
Then look at the retirement accounts you already own.
Look at the agreement you've made.
And ask:
Does my current plan actually match what I believe?
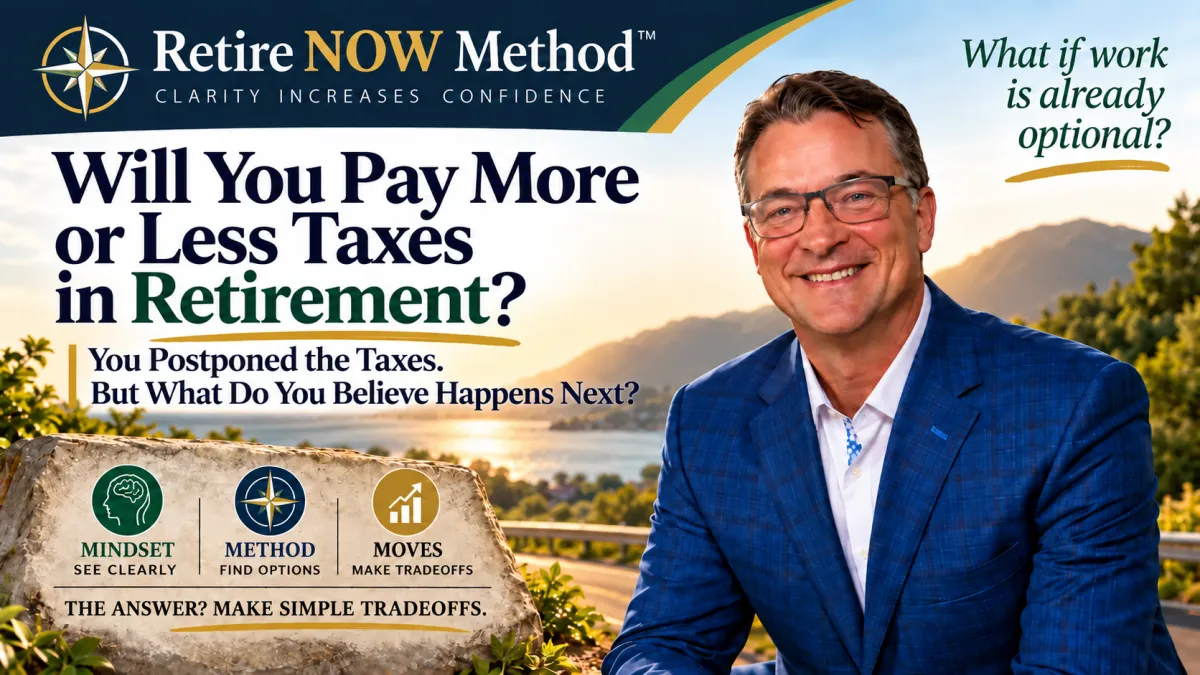
That's the Mindset part of the Retire NOW Method:
See clearly.
Once you can see the agreement clearly, we can look at the Methods available to you.
Then you can decide whether there's a Move worth making.
Because sometimes retirement isn't about accumulating more money.
Sometimes it's about making a better tradeoff with the money you already have.